Understanding Debits and Credits: The Language of Accounting
“Wait, My Bank Says the Opposite!” — debits and credits finally explained in a way that actually makes sense.
Muhammad Hassan Qureshi
BS Accounting & Finance · Future ACCA · Co-founder, LearnFinity
Accounting and finance student at IMSciences Peshawar, AccountingCoach-certified in bookkeeping fundamentals, and teacher of the very concepts in this article.
More about me →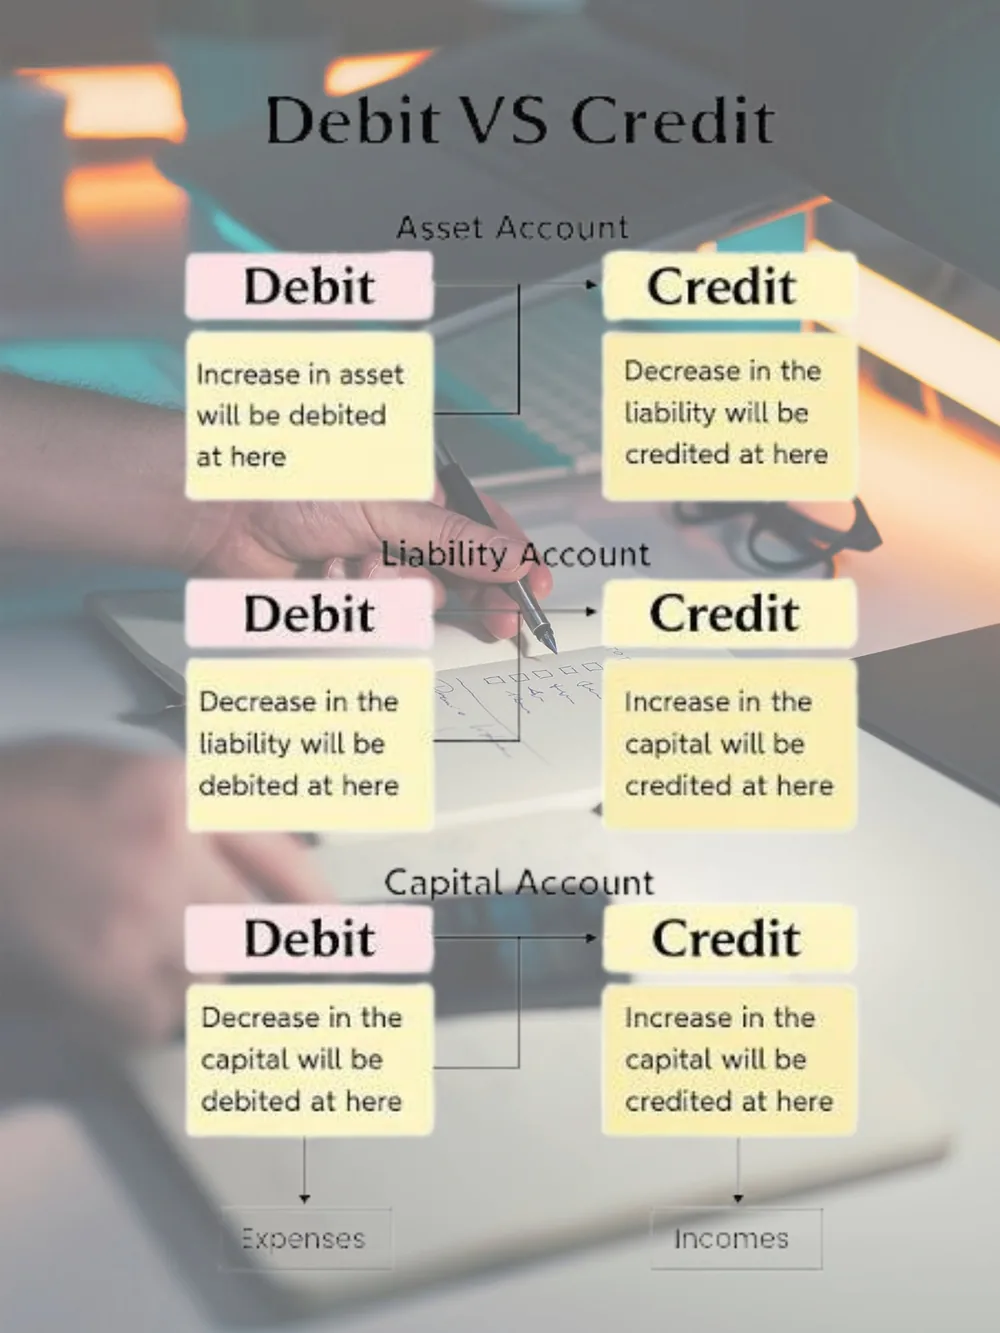
Let me start with a confession. When I first learned about debits and credits, I was completely confused. My bank kept telling me they were “crediting my account” when I got paid, but my accounting textbook said credits decrease cash. Something didn’t add up!
If you’ve ever felt this confusion, trust me — you’re not alone. Today, we’re going to break down debits and credits in a way that actually makes sense. Whether you’re a student like me, a business owner, or just someone curious about how money moves through the business world, this is for you.
§ What exactly are debits and credits?
Think of debits and credits as the left and right sides of a see-saw. Every business transaction affects at least two accounts, and the total debits must always equal the total credits. This is called double-entry accounting, and it’s been the backbone of bookkeeping for centuries.
Here’s the golden rule that took me weeks to memorize but now makes perfect sense:
Simple, right? But here’s where it gets interesting. Different types of accounts behave differently:
Accounts that increase with debits
- Assets (like Cash, Equipment, Inventory)
- Expenses (like Rent, Salaries, Supplies)
- Losses
- Drawing/Dividends accounts
A quick memory trick I use: D-E-A-L — Debits increase Expenses, Assets, and Losses.
Accounts that increase with credits
- Liabilities (like Loans, Accounts Payable)
- Revenues (like Sales, Service Income)
- Gains
- Owner’s Equity
And for this side: G-I-R-L-S — Gains, Income, Revenues, Liabilities, and Stockholders’ Equity increase with credits.
§ The cash rule that changed everything
Here’s a tip that transformed my understanding: Whenever cash is RECEIVED, debit Cash. Whenever cash is PAID OUT, credit Cash.
Let’s see this in action with a real example. Imagine your business performs a service worth $500 and the customer pays immediately. You’d debit Cash $500 (increase your cash) and credit Service Revenue $500 (increase your income).
But what if the customer says, “I’ll pay you in 30 days”? Then you’d debit Accounts Receivable $500 (an asset representing money owed to you) and credit Service Revenue $500. Same revenue — different debit — because the cash hasn’t arrived yet.
§ Visualizing with T-accounts
Accountants love T-accounts. They look like the letter “T” with debits on the left and credits on the right. Here’s a quick example:
Your company borrows $5,000 from a bank. To record this:
| Account | Entry | Amount |
|---|---|---|
| Cash (Asset) | Debit | $5,000 |
| Notes Payable (Liability) | Credit | $5,000 |
Later, you repay $2,000:
| Account | Entry | Amount |
|---|---|---|
| Notes Payable | Debit | $2,000 |
| Cash | Credit | $2,000 |
See how one account is debited and another is credited? That’s double-entry in action!
§ Why your bank says the opposite
Remember my confusion about banks? Here’s the deal: when your bank “credits” your account, they’re actually increasing a liability on their own books. From the bank’s perspective, your money is their liability — they owe it back to you! So when they credit your account, they’re increasing what they owe you.
When they “debit” your account for a monthly fee, they’re reducing what they owe you. Make sense now? Both perspectives are correct; it’s just about who’s looking at the accounts.
§ Putting it all together
The beauty of understanding debits and credits is that it gives you X-ray vision into business transactions. You can look at any financial transaction and understand exactly how it affects the company’s financial position.
As I continue my journey through the AccountingCoach course — which led to my certification in this exact material — I’m realizing that mastering these basics is like learning the ABCs of business. Everything else builds on this foundation.
§ Your next steps
Don’t get discouraged if this seems overwhelming at first. Start with the basic rules:
- Debit = Left | Credit = Right
- Cash received = Debit Cash
- Cash paid = Credit Cash
- Assets increase with debits
- Liabilities and Equity increase with credits
Practice with simple transactions until they become second nature. Before you know it, you’ll be thinking in debits and credits without even trying!
Written by Muhammad Hassan Qureshi
BS Accounting & Finance · Future ACCA
I teach accounting, commerce, economics and maths — and I write one article like this every few weeks. If this helped, the best thanks is sharing it with one student who needs it.
Talk to me on WhatsApp →